2.24 - Asymmetric Information
The definition of asymmetric information
Asymmetric information arises in a market when one side of a transaction possesses more or better details than the other. This imbalance disrupts efficient resource allocation, leading to market failure. It creates two main issues: adverse selection and moral hazard.
Adverse selection and its examples
Adverse selection happens before a transaction, when one party has superior knowledge about the product or service, causing the market to favour poorer quality options over time.
Examples of adverse selection
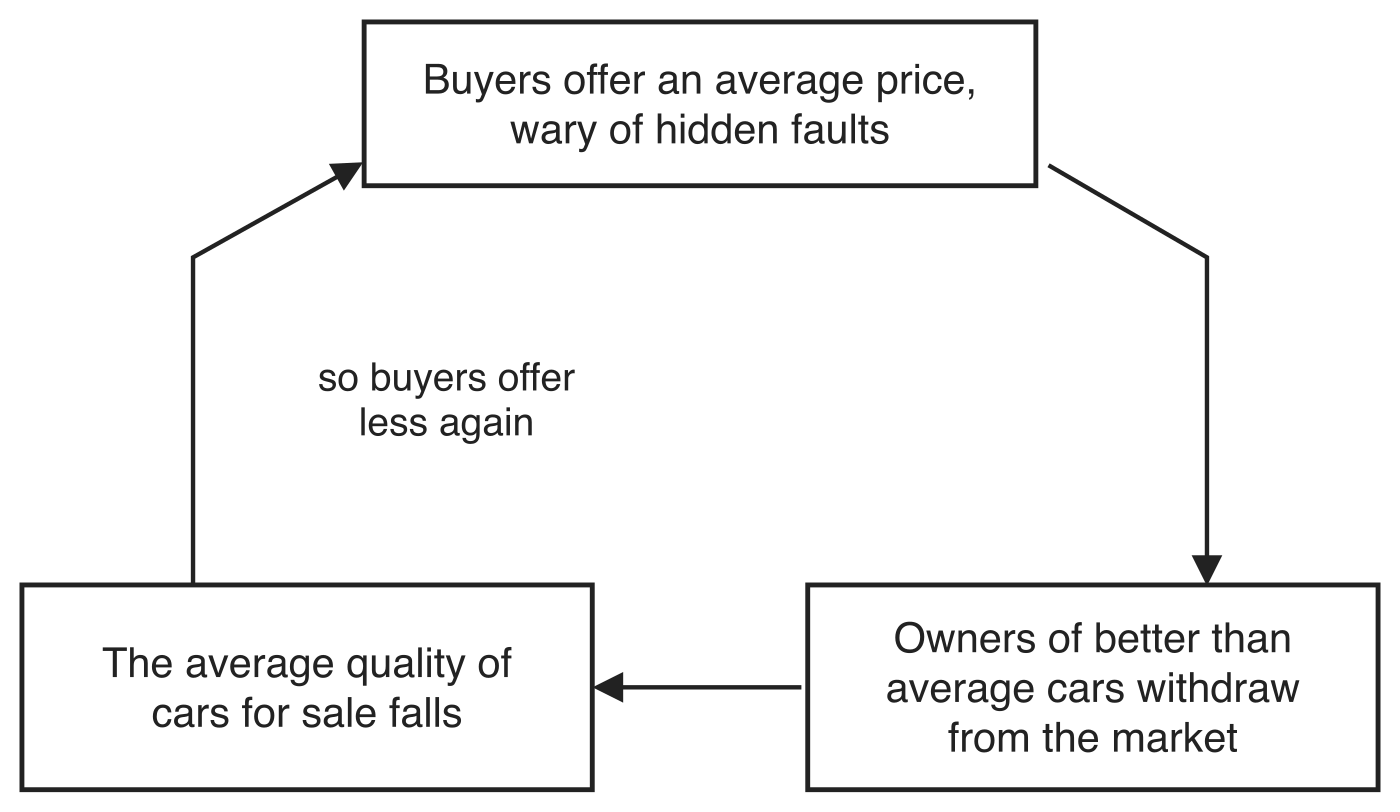
- Used car market - Sellers know more about a vehicle's true condition than buyers, so buyers offer an average price, wary of hidden faults. At that price, owners of better than average cars withdraw from the market. The average quality of cars for sale falls, so buyers offer less again, and each turn of the cycle thins the market further until it may collapse.
- Health insurance market - Insurers struggle to assess applicants' true health risks. Low-risk individuals see premiums as too high and opt out, leaving mostly high-risk clients. Insurers raise rates to cover claims, pushing more low-risk people away and potentially collapsing the market.
The diagram below traces the cycle in the used car market; the health insurance market runs the same cycle with premiums in place of prices.
Moral hazard and its examples
Moral hazard emerges after a contract, where one party changes behaviour in a way that increases risk, knowing the costs fall on the other party. This stems from hidden actions that are hard to monitor.
Examples of moral hazard
- Car insurance - Drivers with full coverage might drive more carelessly, such as speeding or neglecting maintenance, since the insurer covers accident costs.
- Bank lending - Banks with government guarantees on deposits may lend riskier, knowing taxpayers could bail them out if loans fail, rather than assessing borrowers carefully.
Government responses to asymmetric information
Governments intervene to correct information imbalances, aiming to improve market efficiency and protect participants.
Legislation and regulation
Governments set minimum standards for quality and safety, while overseeing firm conduct to reduce failures from information gaps.
Drawbacks of legislation and regulation:
- These processes involve heavy bureaucracy.
- Monitoring and enforcement carry high opportunity costs.
- Firms face increased expenses.
Provision of information
Governments supply data to help consumers make informed choices, such as through public awareness campaigns or mandatory disclosures.
Drawbacks of providing information:
- Gathering and distributing accurate details is challenging.
- Ensuring the information remains current and reliable requires ongoing effort.
Private responses to asymmetric information
Market participants use strategies like signalling and screening to bridge information gaps without government help.
Signalling and screening differ in which side of the transaction acts on the information gap, as the table below sets out.
| Strategy | Which party acts | What it involves | Examples |
|---|---|---|---|
| Signalling | The informed party | Sharing credible details to build trust | High-end clothing brands provide detailed certifications of material authenticity to assure buyers of quality; universities offer prestigious degrees to signal academic rigour and attract top students and employers |
| Screening | The less-informed party | Using observable traits to gather insights | Insurers require medical exams before issuing life policies to identify high-risk applicants and adjust premiums; rental companies check credit scores and references to screen tenants, reducing the chance of non-payment or damage |