3.4 - Equilibrium
Short-run macroeconomic equilibrium
Short-run macroeconomic equilibrium occurs when the total quantity of goods and services demanded matches the total supplied at a given price level.
Determining equilibrium output and price level
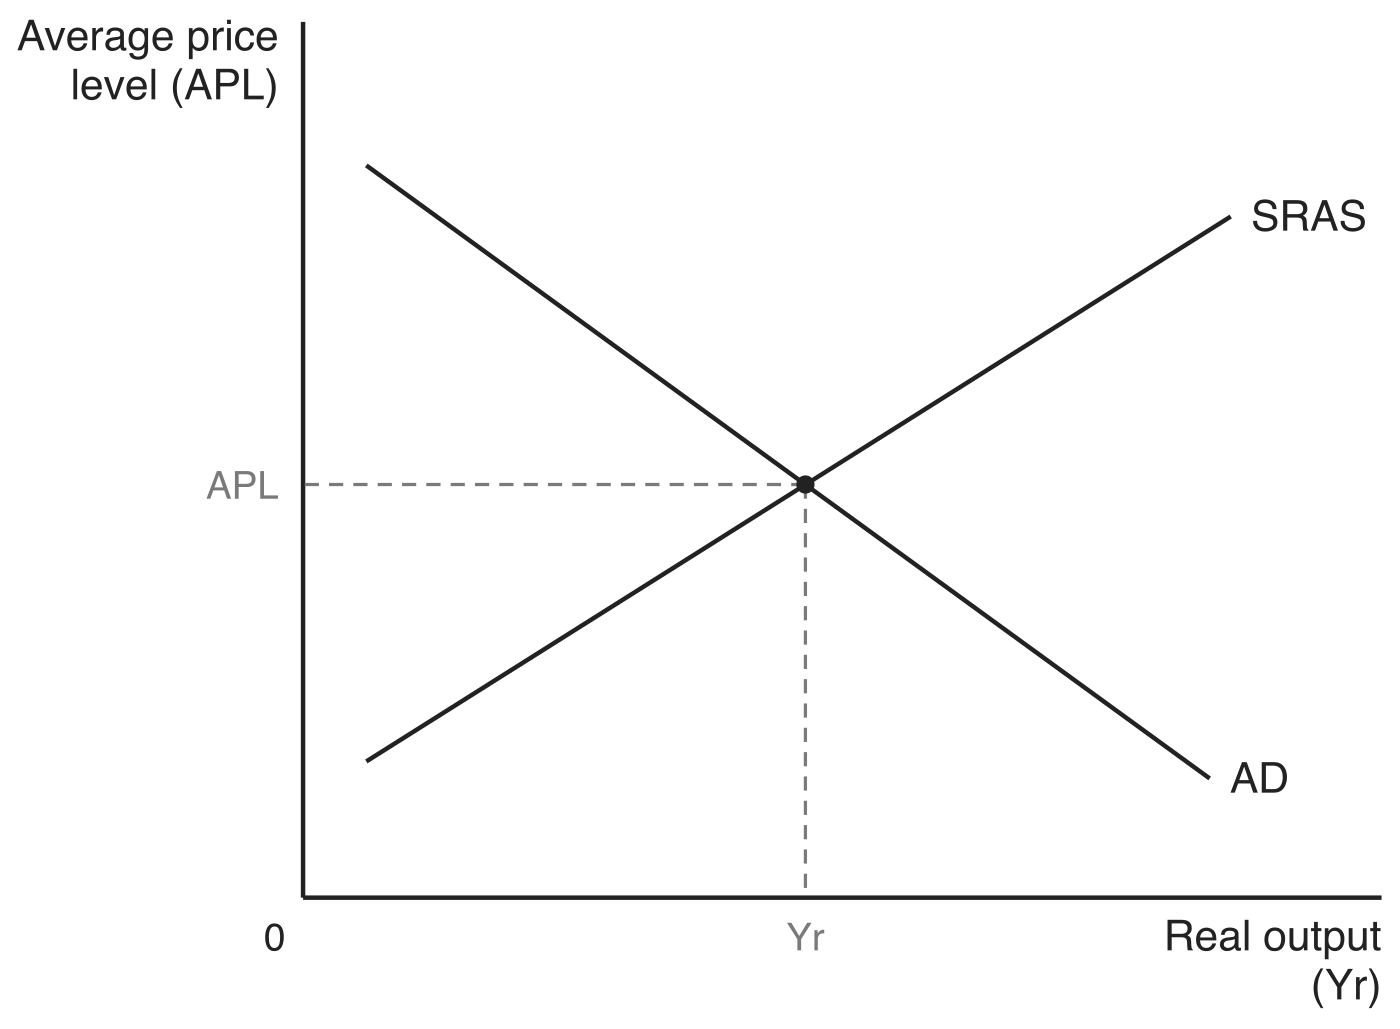
- Equilibrium real output is found where the aggregate demand (AD) curve intersects with the short-run aggregate supply (SRAS) curve.
- The average price level (APL) is set at this intersection, reflecting the general cost of goods and services across the economy.
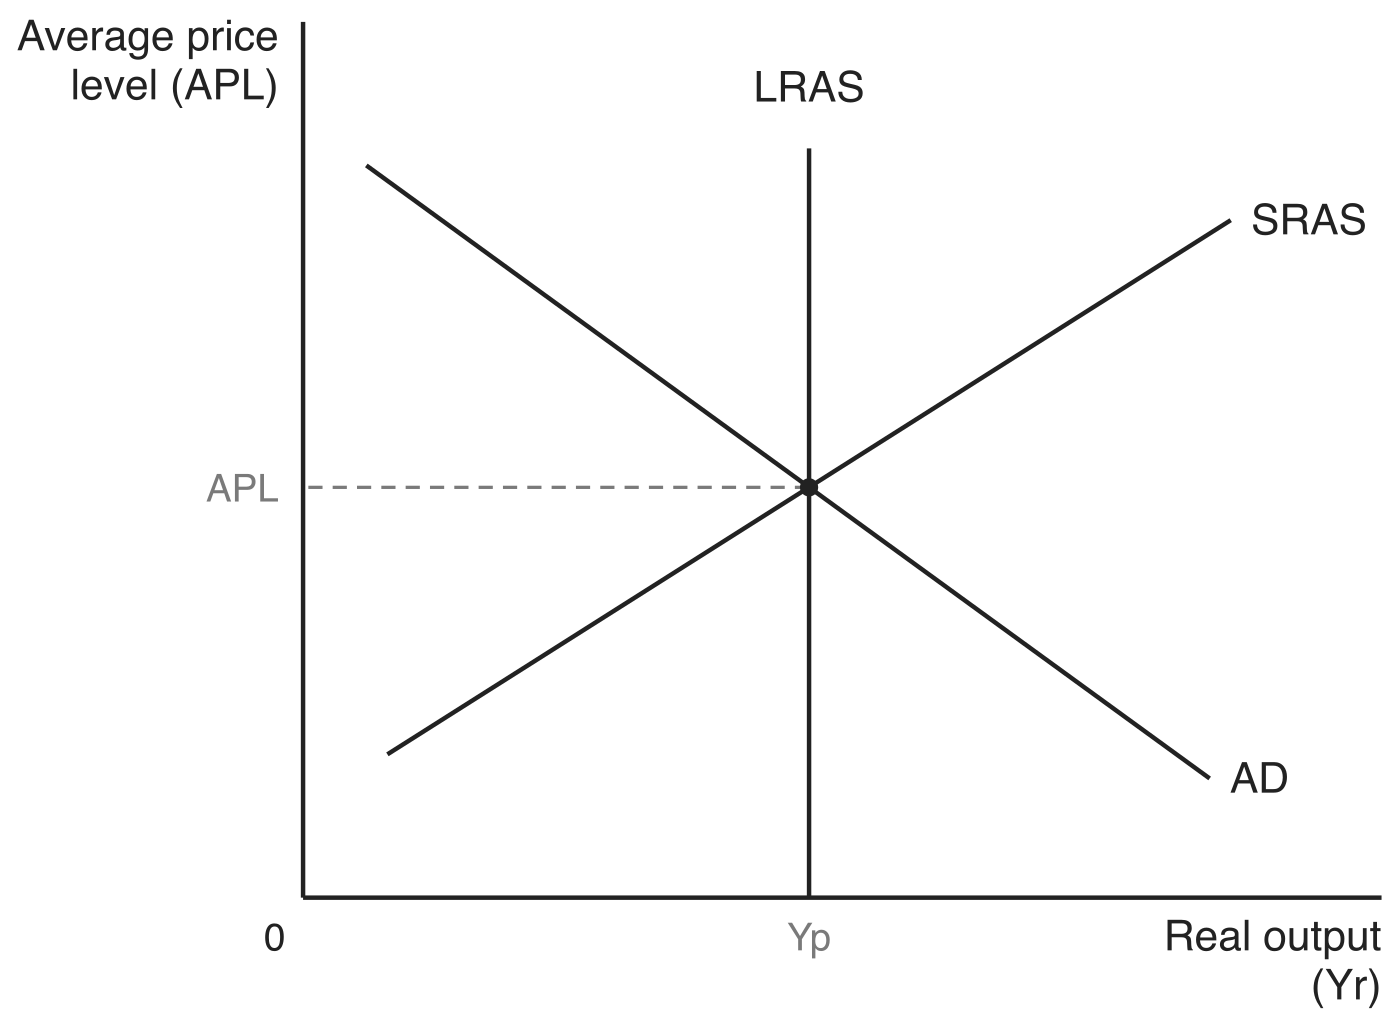
The diagram below shows this. Where AD cuts SRAS, the economy settles at real output Yr and average price level APL, and at that combination the total quantity demanded matches the total quantity supplied, so neither output nor prices are under pressure to change.
Changes in equilibrium from shifts in AD and SRAS
Shifts in either AD or SRAS alter the economy's equilibrium, affecting both output and prices.
Effects of shifts in aggregate demand
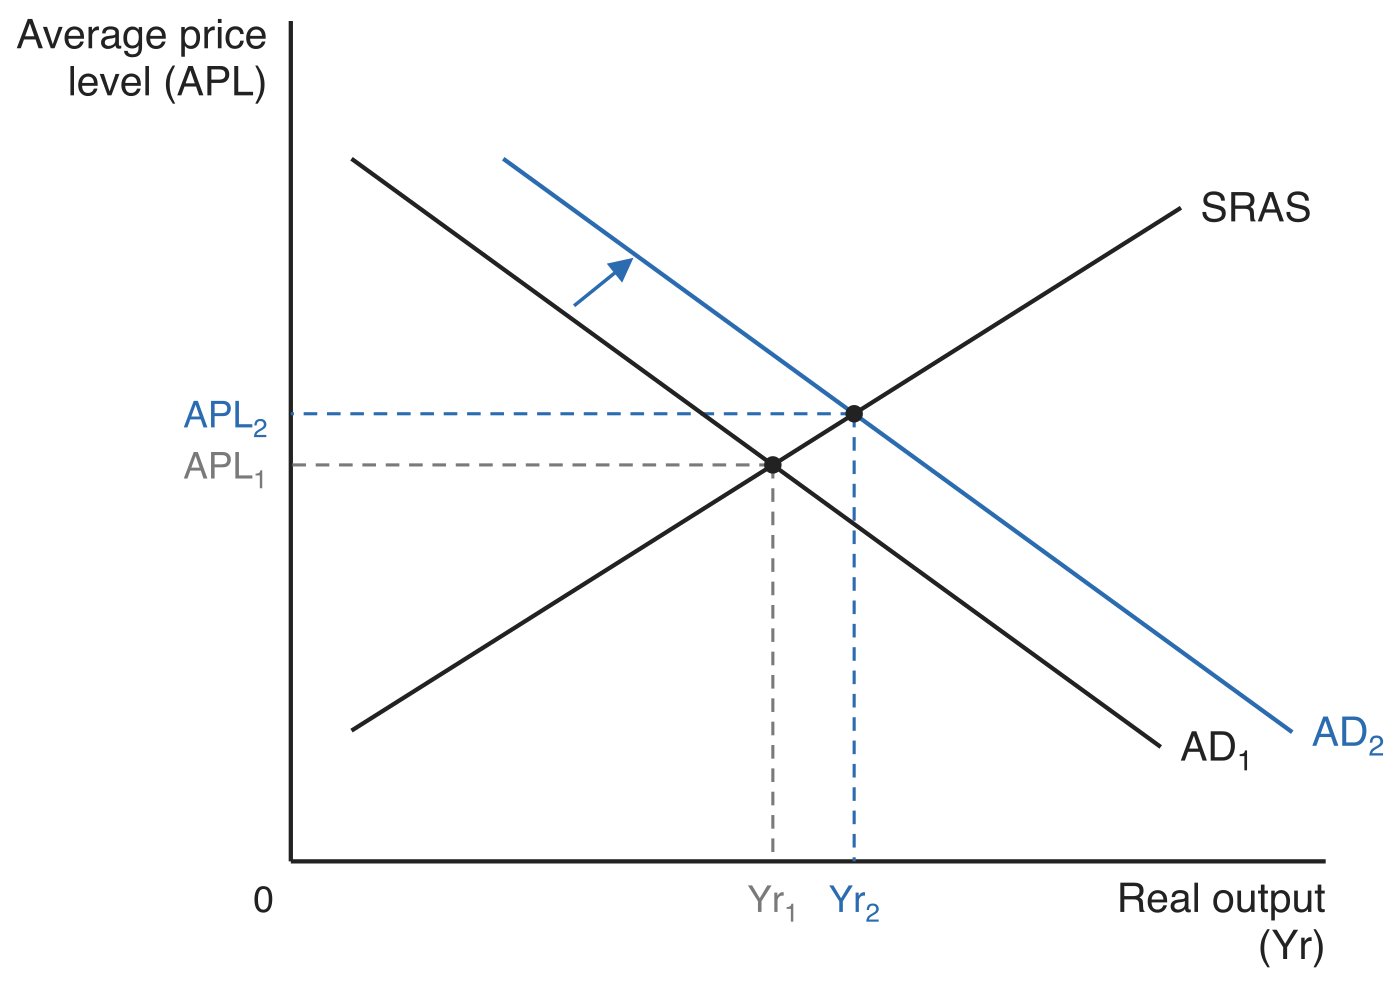
- An increase in AD, such as from government spending boosts, shifts the AD curve rightwards.
- This results in higher real output and a higher APL in the short run.
- A decrease in AD shifts the curve leftwards, leading to lower real output and a lower APL.
The diagram below shows an increase in aggregate demand. AD1 shifts rightwards to AD2 along an unchanged SRAS curve, so equilibrium real output rises from Yr1 to Yr2 and the average price level rises from APL1 to APL2. A decrease in AD works the other way: the curve shifts leftwards and both real output and the APL end up lower.
Effects of shifts in short-run aggregate supply
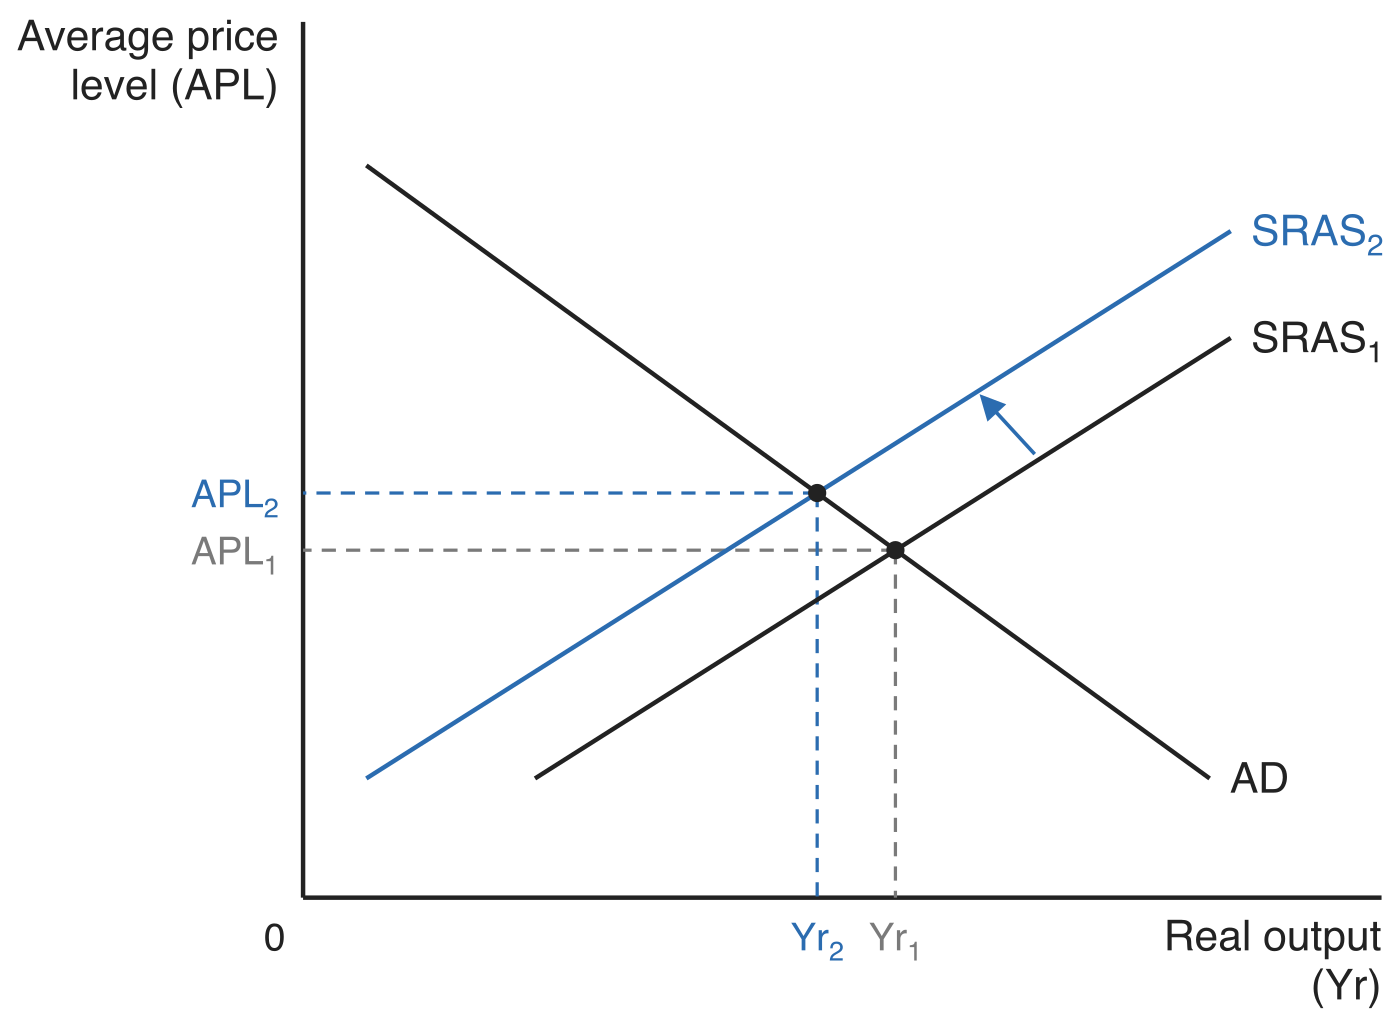
- A decrease in SRAS, caused by rising production costs like increased commodity prices, shifts the SRAS curve leftwards.
- This leads to a higher APL but lower equilibrium real output.
- An increase in SRAS shifts the curve rightwards, resulting in a lower APL and higher real output.
The diagram below shows a decrease in short-run aggregate supply. SRAS1 shifts leftwards to SRAS2 against an unchanged AD curve, so the average price level rises from APL1 to APL2 while equilibrium real output falls from Yr1 to Yr2. An increase in SRAS reverses both effects, shifting the curve rightwards to give a lower APL and higher real output.
Long-run macroeconomic equilibrium
In the long run, the economy adjusts to its full potential, where resources are fully utilised.
Key features of long-run equilibrium
- Equilibrium output settles at the potential or full-employment level, regardless of short-term fluctuations.
- Short-run deviations from potential output occur because nominal wages are fixed in the short run.
- In the long run, nominal wages become flexible, adjusting fully to changes in the APL, restoring the economy to its natural capacity.
The diagram below shows long-run equilibrium. The long-run aggregate supply (LRAS) curve is vertical at potential output Yp, and AD cuts SRAS on that vertical line, so the economy produces Yp at an average price level of APL. Because LRAS is fixed at Yp, this is the only level of output the economy can sustain once nominal wages have fully adjusted.
Deflationary and inflationary gaps
Gaps arise when the economy's actual output diverges from its potential.
Types of economic gaps
- Deflationary gap - Occurs when equilibrium real output falls below the full-employment level, indicating unused resources.
- Inflationary gap - Exists when equilibrium real output exceeds the full-employment level, leading to pressure on resources.
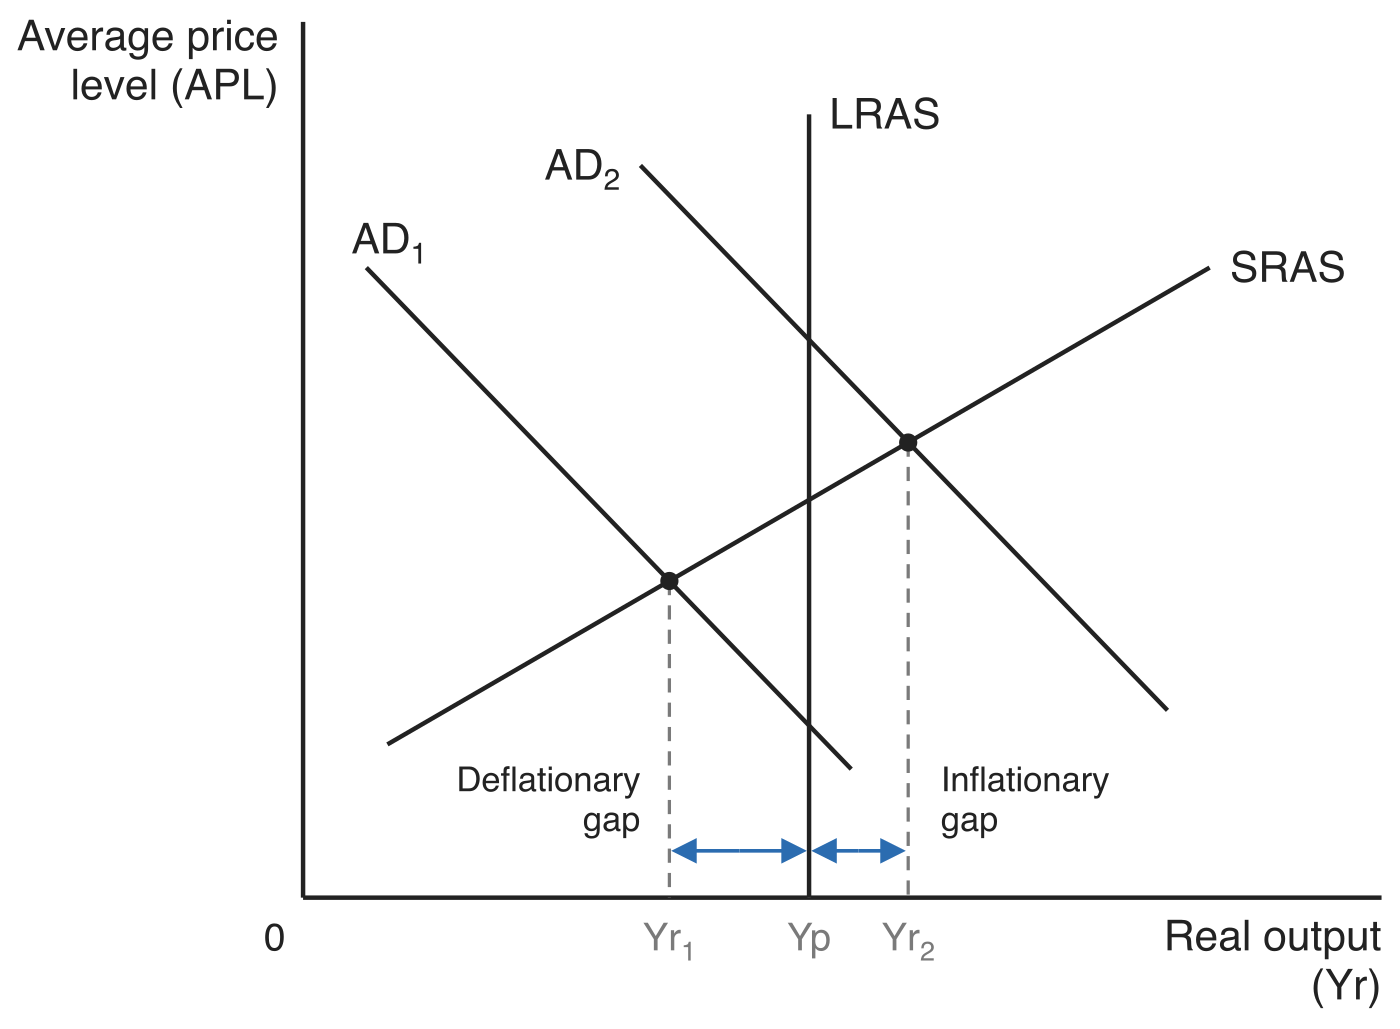
The diagram below shows both cases against the same vertical LRAS curve at potential output Yp. With aggregate demand at AD1, SRAS and AD1 meet at real output Yr1, which falls short of Yp, and the horizontal distance from Yr1 to Yp is the deflationary gap. With demand instead at AD2, equilibrium output is Yr2, beyond Yp, and the distance from Yp to Yr2 is the inflationary gap.
Monetarist and Keynesian views on closing gaps
Different economic schools offer contrasting explanations for how gaps are resolved, focusing on market mechanisms versus government action.
Monetarist perspective on gap closure
- Market forces naturally eliminate both deflationary and inflationary gaps through adjustments in nominal wages.
- No government intervention is required, as the economy self-corrects over time.
- The adjustment process may take a considerable period, reflecting the "long run" nature of these changes.
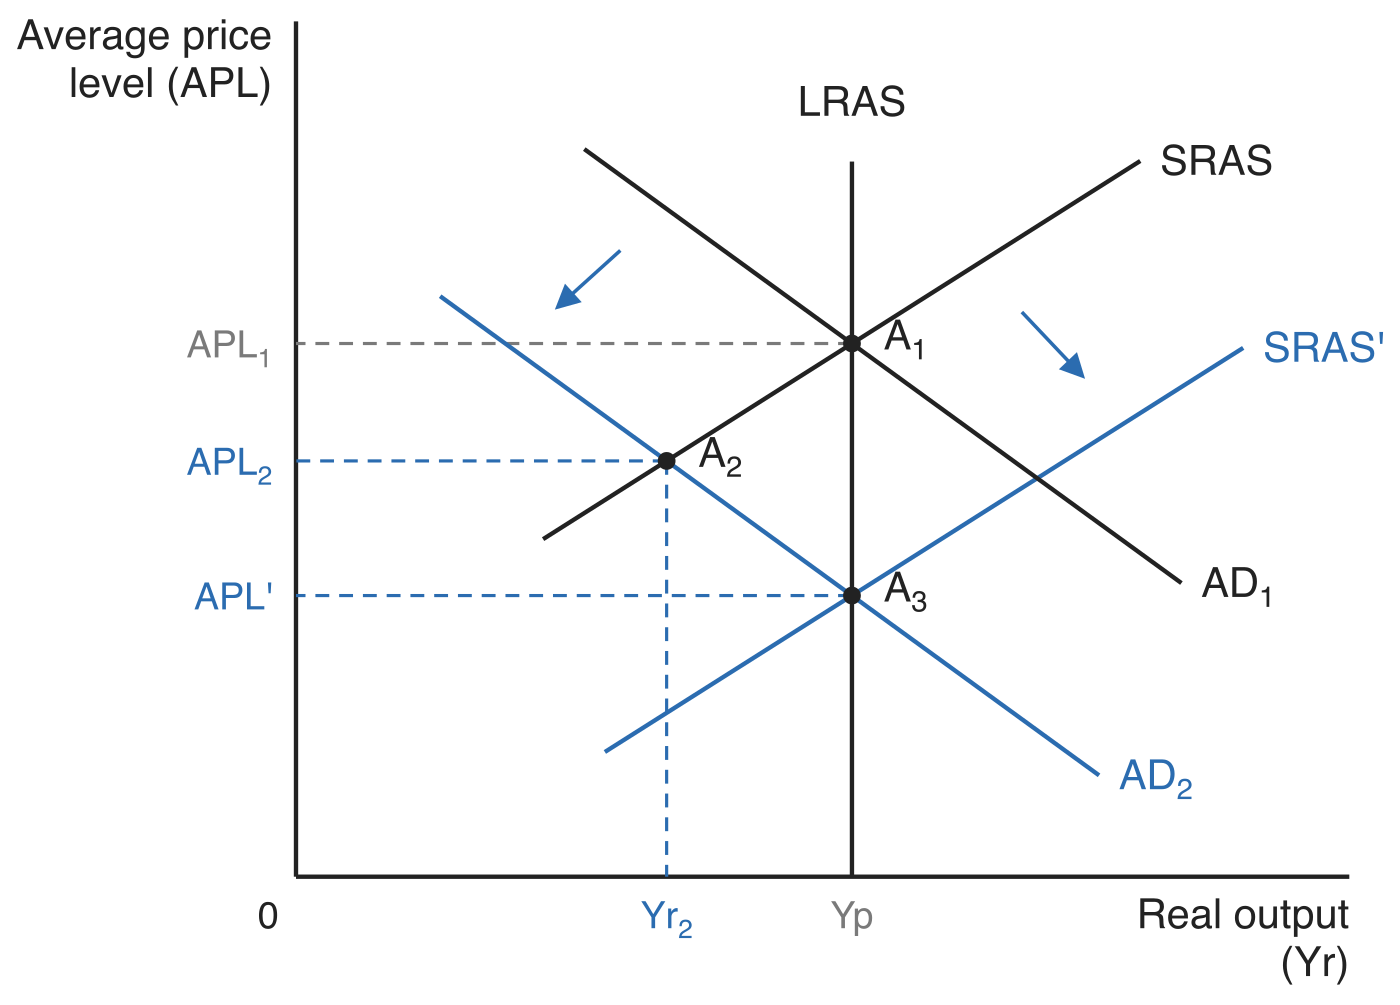
The diagram below traces how a deflationary gap closes. The economy starts at A1, where AD1 crosses SRAS on the LRAS curve, so output sits at potential Yp and the average price level at APL1. A fall in aggregate demand to AD2 moves the short-run equilibrium down the SRAS curve to A2, where output has dropped to Yr2 and the price level to APL2, leaving a deflationary gap. The lower price level then drags nominal wages down, short-run aggregate supply increases to SRAS', and the economy reaches A3 with output back at Yp and the price level lower still at APL'.
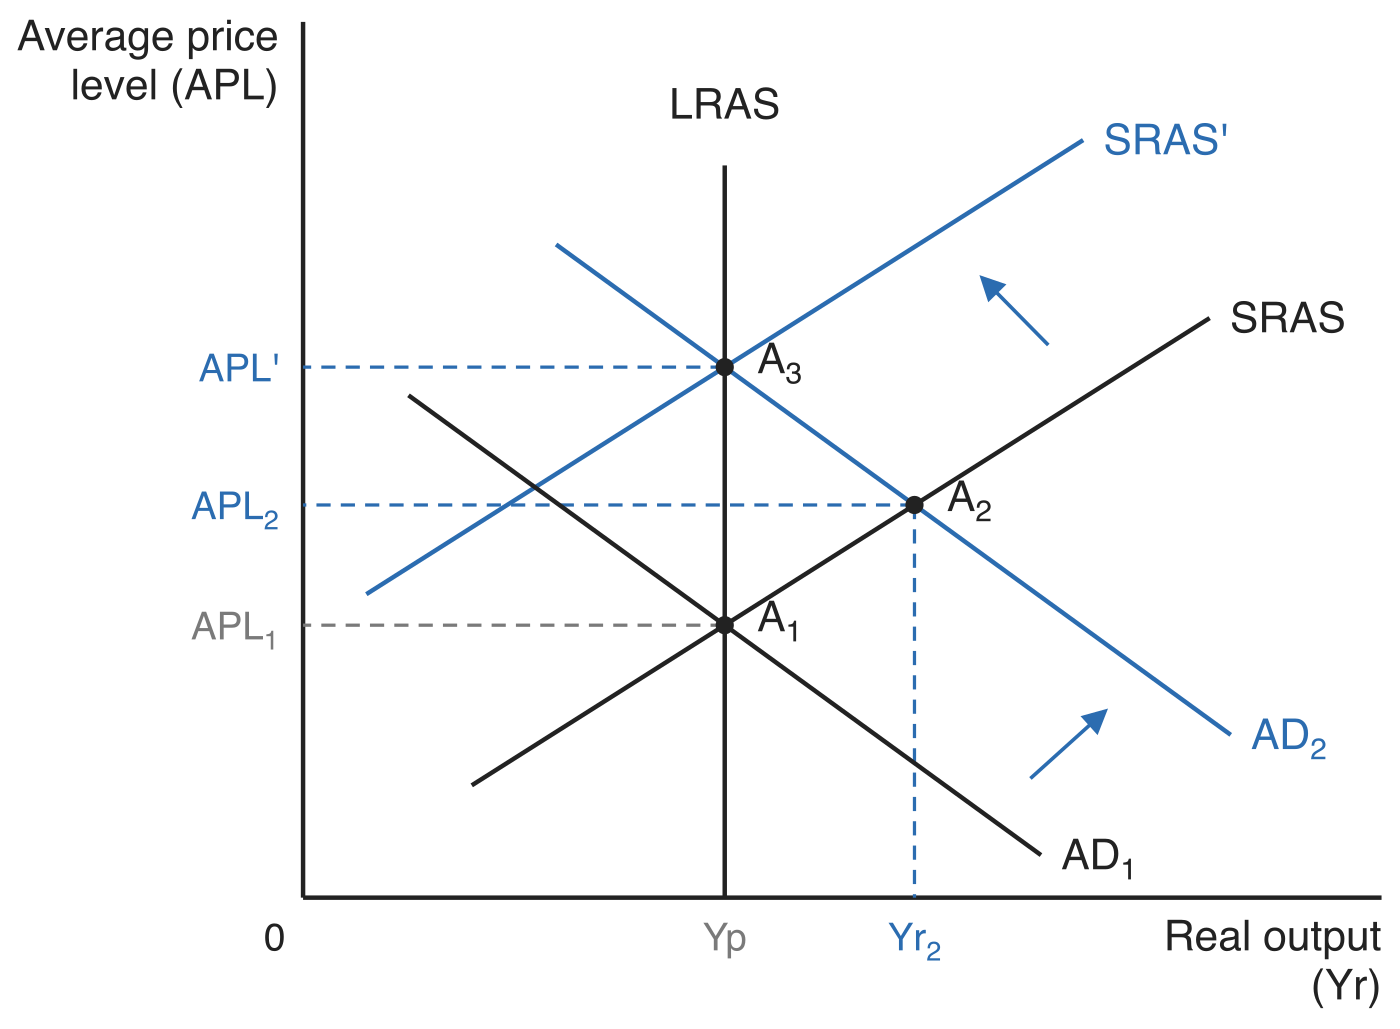
An inflationary gap closes by the mirror route, shown in the diagram below. From A1 at Yp and APL1, a rise in aggregate demand from AD1 to AD2 carries the economy up SRAS to A2, where output Yr2 exceeds Yp and the price level has risen to APL2. Nominal wages then rise, short-run aggregate supply falls to SRAS', and the economy settles back on LRAS at A3: output is at Yp again, but the average price level is higher at APL'.
Keynesian perspective on gap closure
- Unlike Monetarists, Keynesians argue there is no automatic mechanism to close gaps, potentially leaving the economy stuck below full employment.
- Nominal wages are "sticky downwards," meaning they rise easily but resist falling, prolonging deflationary gaps.
- AD drives the equilibrium level of activity, so a fall in AD can trap the economy in a deflationary gap.
- Government intervention is essential, using expansionary fiscal policy (e.g., increased spending) or loose monetary policy (e.g., lower interest rates) to boost AD and restore full employment.
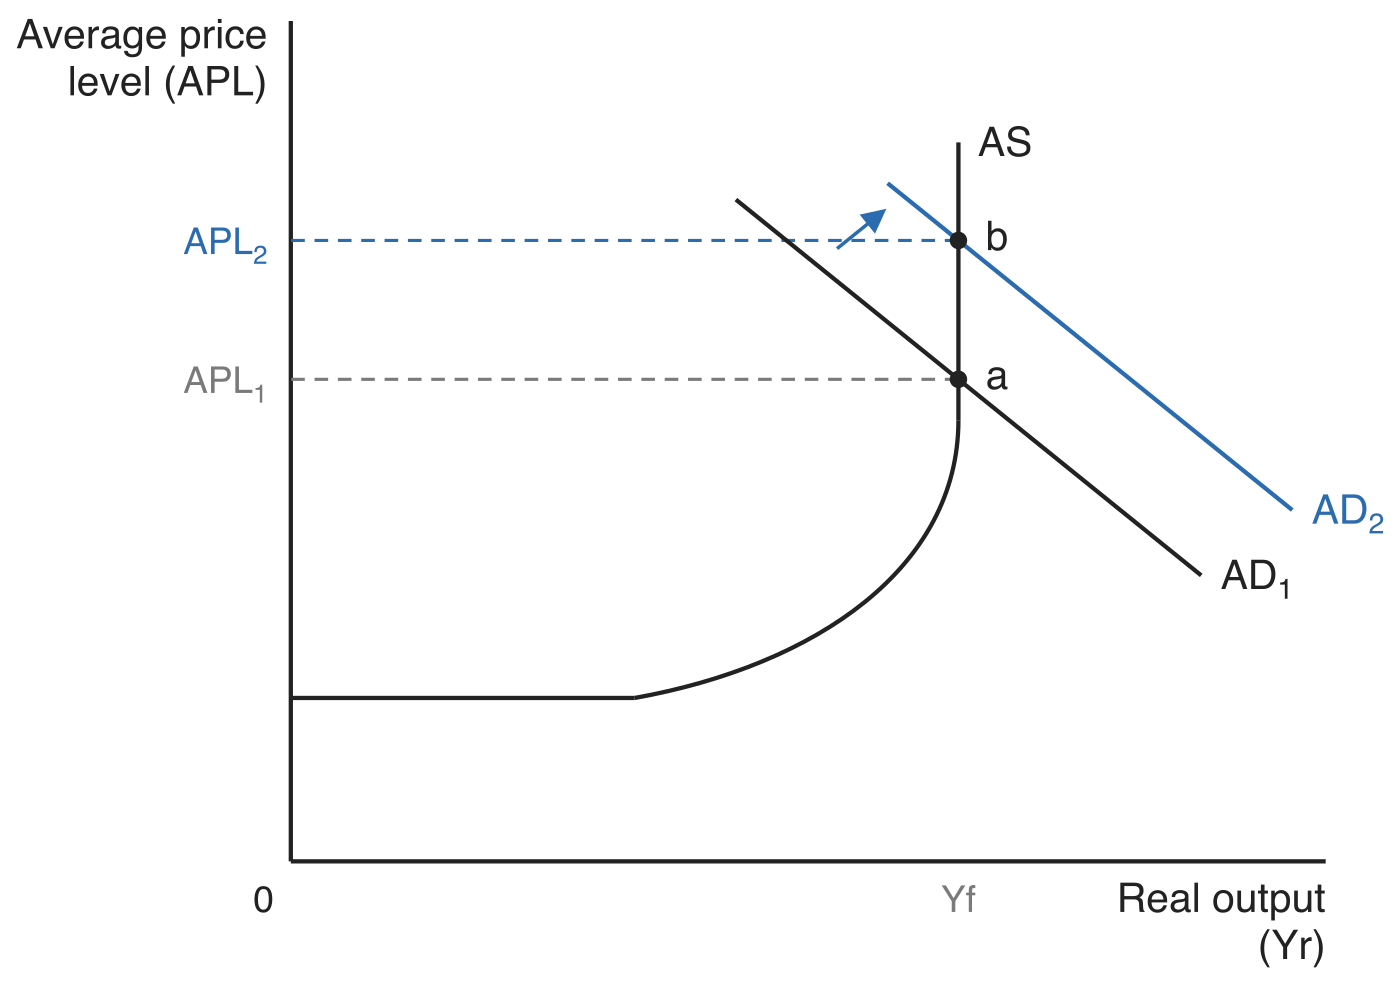
- At full employment, further AD increases cause inflation without output growth.
- On a strict reading of the Keynesian model, full employment means zero unemployment, but a natural rate can be built in by placing full-employment output to the left of where AS turns vertical.
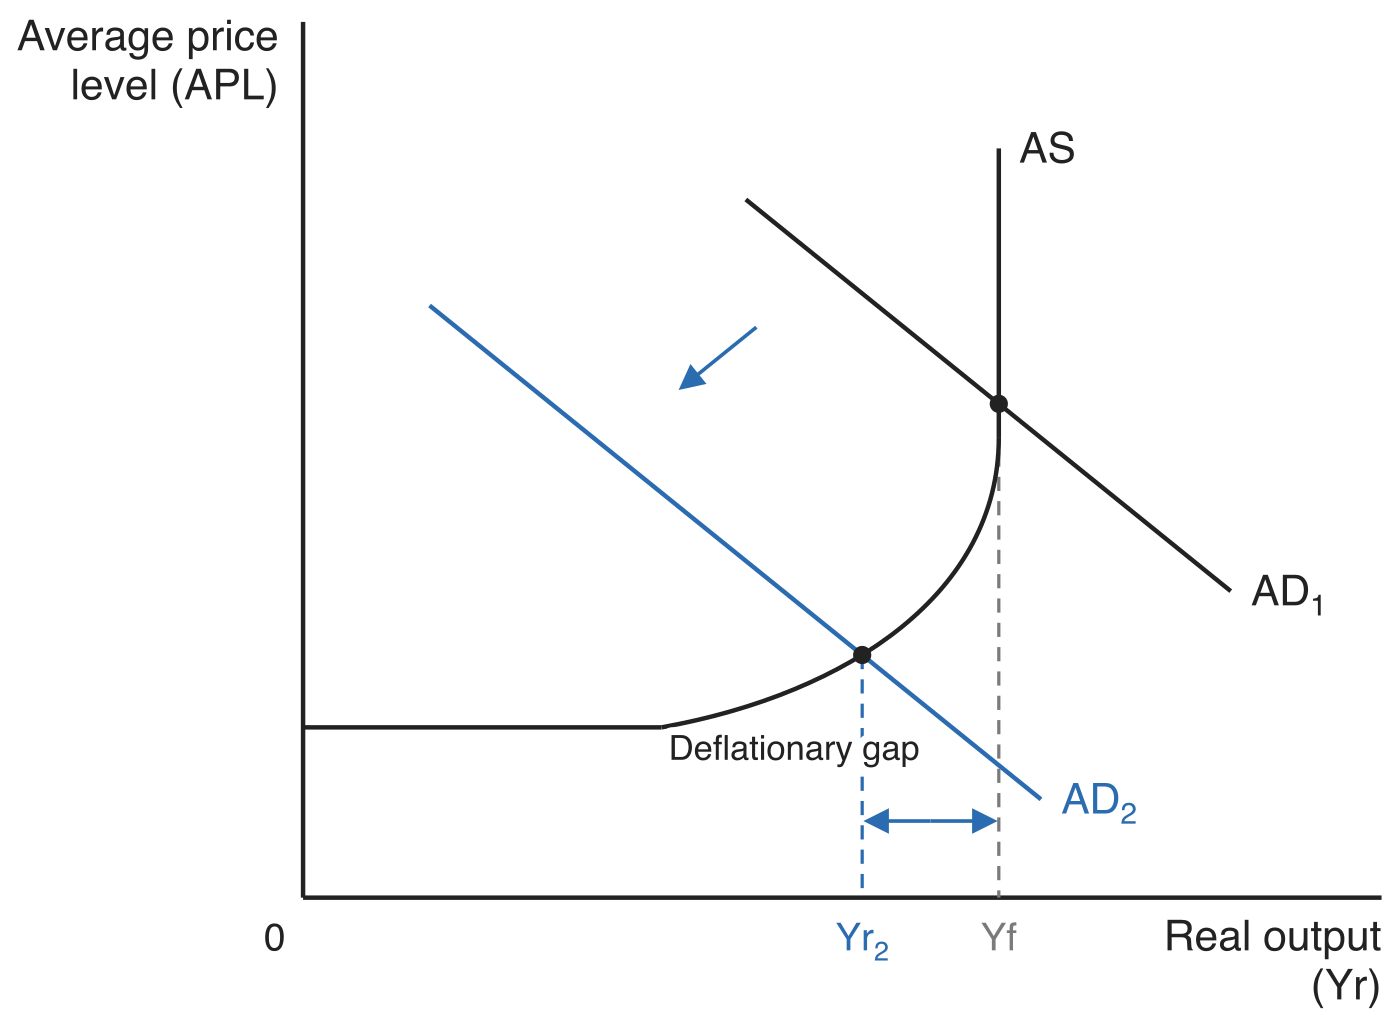
The diagram below shows the Keynesian version of a deflationary gap. The economy starts at full employment, where AD1 meets the vertical section of the AS curve at Yf. A collapse in confidence shifts aggregate demand left to AD2, and equilibrium output falls back to Yr2 on the sloped part of AS, opening the deflationary gap marked between Yr2 and Yf. Because nominal wages will not fall, nothing closes that gap on its own.
Once the economy is already at Yf, extra demand has nowhere to go. In the diagram below, aggregate demand rising from AD1 to AD2 moves the economy up the vertical section of AS from point a to point b: the average price level climbs from APL1 to APL2 while real output stays at Yf, so the extra demand buys inflation and no extra output.