3.21 - Monetary Policy & Interest Rates
Expansionary and contractionary monetary policy
Monetary policy involves actions by central banks to influence the money supply and interest rates, aiming to achieve economic goals such as stable prices, full employment, and growth. It can be expansionary or contractionary depending on the economic conditions.
Expansionary monetary policy
Expansionary policy, also known as loose or easy policy, aims to boost aggregate demand (AD) during recessions or high unemployment. This is achieved by lowering interest rates to encourage borrowing and spending.
Contractionary monetary policy
Contractionary policy, also known as tight policy, seeks to reduce AD to combat inflation. This involves raising interest rates to discourage borrowing and spending.
Summary of monetary policy effects
| Effect on | Expansionary policy | Contractionary policy |
|---|---|---|
| Money supply (Ms) | Increases (Ms↑) | Decreases (Ms↓) |
| Interest rates (r) | Fall (r↓) | Rise (r↑) |
| Consumption (C) | Rises (C↑) | Falls (C↓) |
| Investment (I) | Rises (I↑) | Falls (I↓) |
| Net exports (NX) | Rise (NX↑) | Fall (NX↓) |
| Aggregate demand (AD) | Rises (AD↑) | Falls (AD↓) |
How central banks adjust interest rates
Central banks manipulate interest rates by altering the money supply through various tools. These adjustments create imbalances in the money market, prompting changes in rates.
Tools used by central banks to change interest rates
- Open market operations - The most common method, involving buying or selling government bonds to adjust the money supply.
- Required reserve ratio - Altering the proportion of deposits banks must hold as reserves, which affects how much they can lend.
- Discount rate - Changing the rate at which banks borrow from the central bank, influencing overall lending rates.
Process of decreasing interest rates
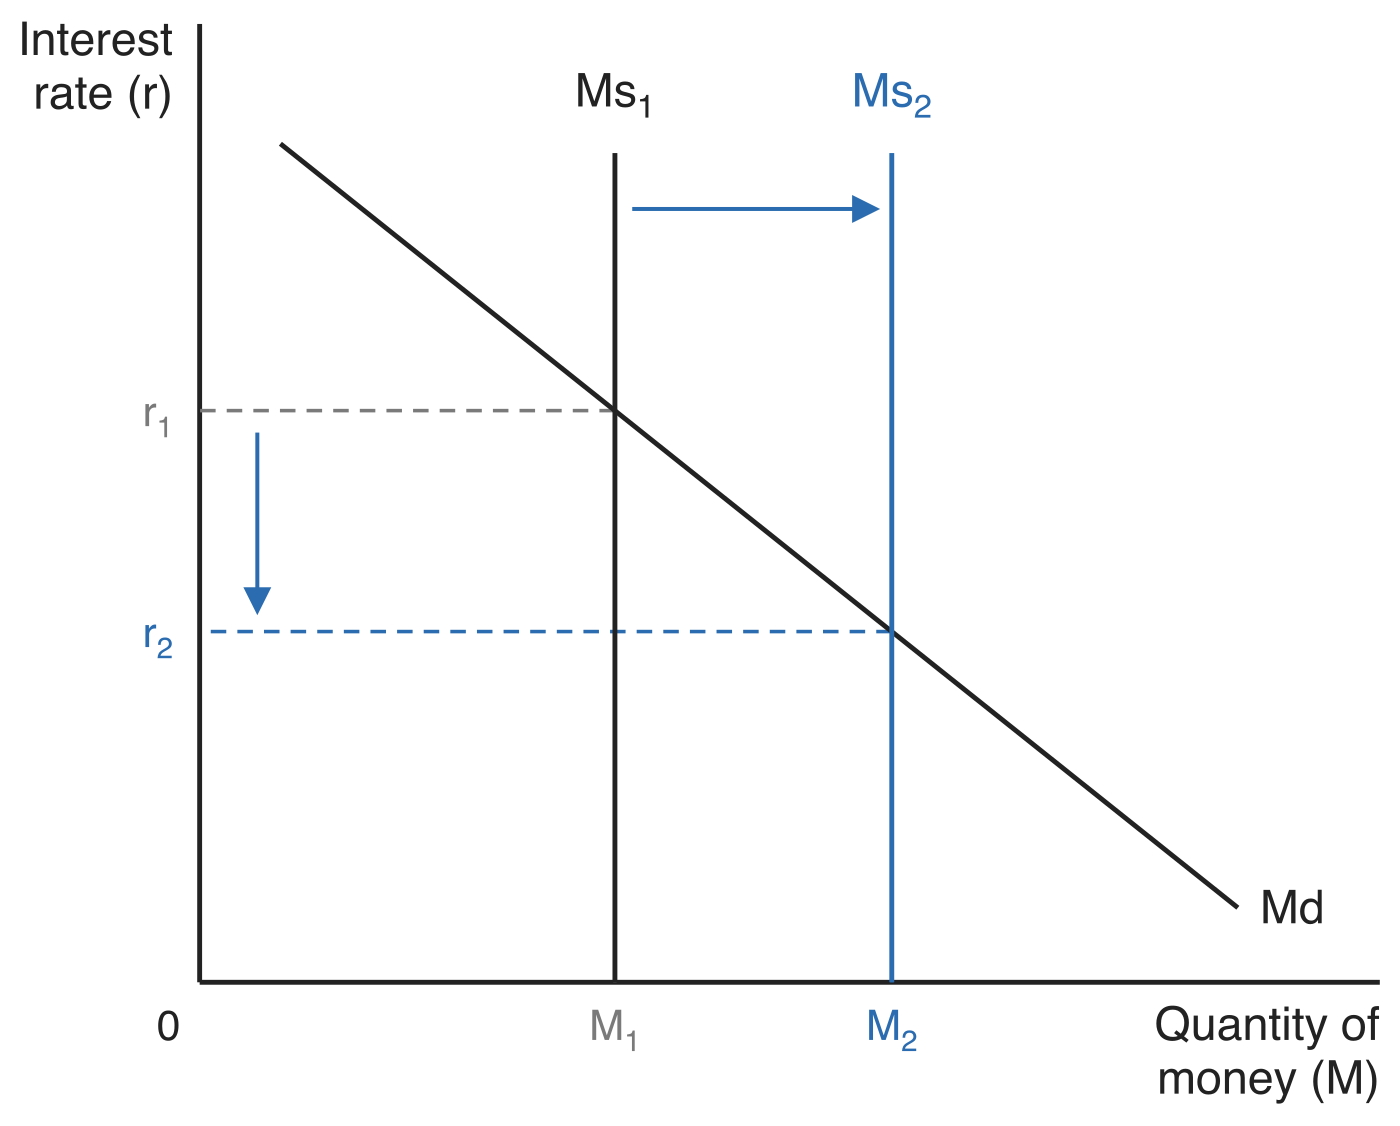
To lower rates, the central bank increases the money supply from Ms1 to Ms2. This creates an excess supply of money in the market, reducing interest rates as funds become more available.
The diagram below shows this. At the original interest rate r1 the enlarged money supply Ms2 exceeds the demand for money Md, and that excess supply pushes the rate down to r2, where the quantity of money held has risen from M1 to M2.
Process of increasing interest rates
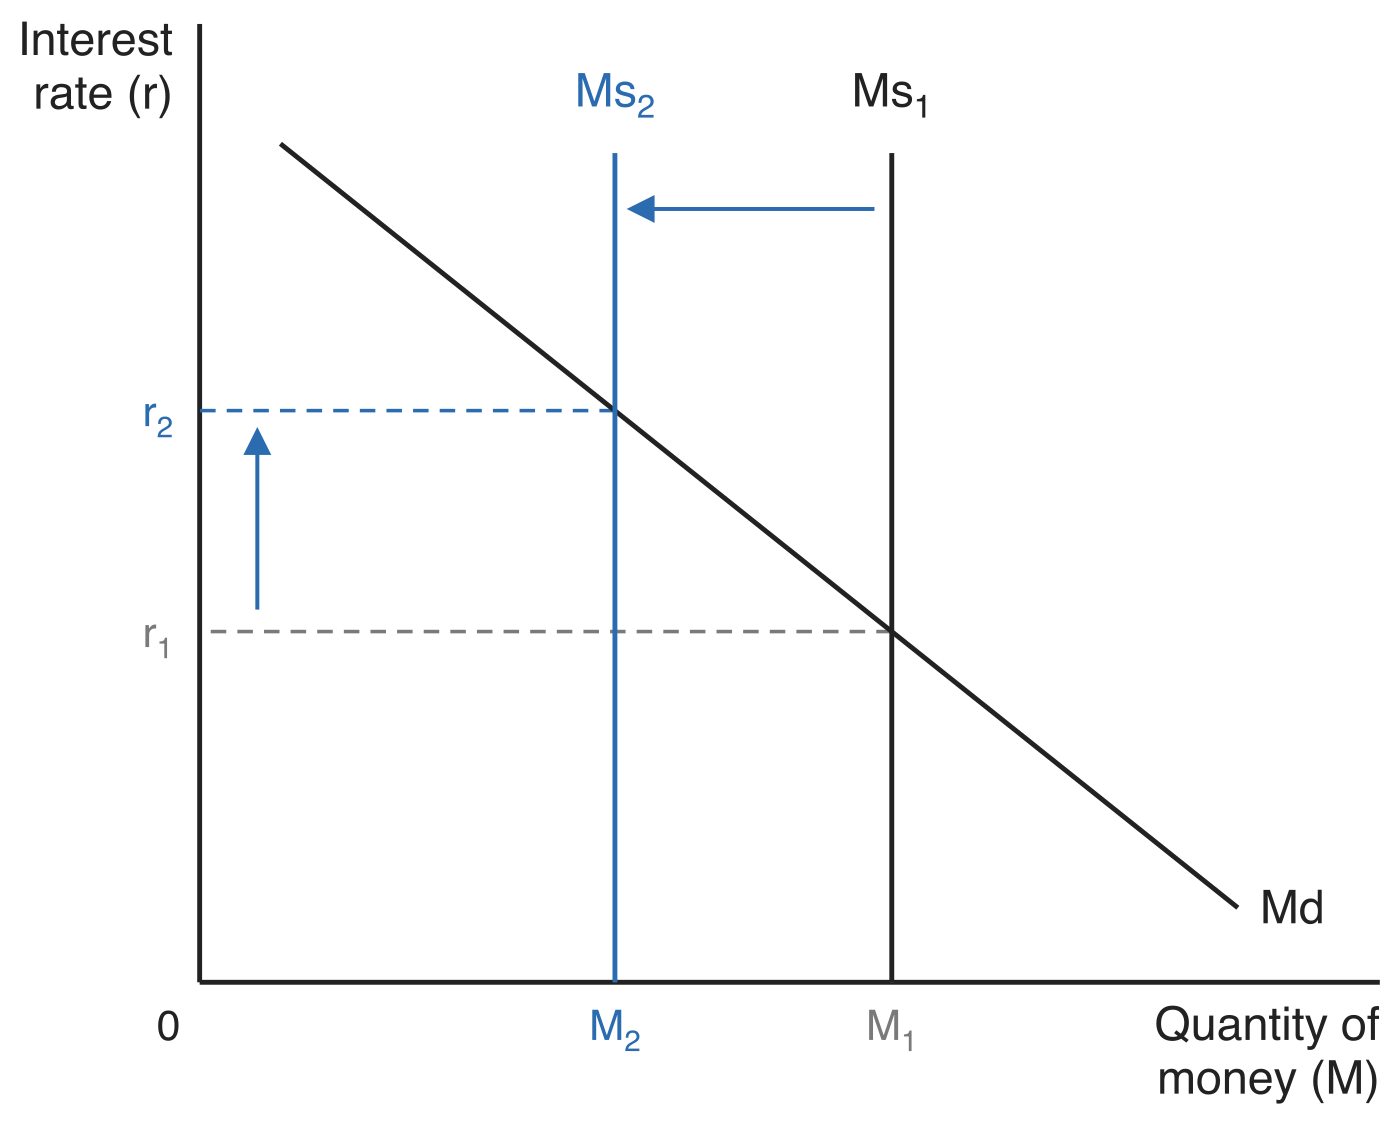
To raise rates, the central bank decreases the money supply from Ms1 to Ms2. This generates excess demand for money, increasing interest rates as borrowing becomes more competitive.
The diagram below shows the same market in reverse. At the original interest rate r1 the demand for money Md now exceeds the reduced supply Ms2, and that excess demand pulls the rate up to r2, with the quantity of money held falling from M1 to M2.
Effects of expansionary monetary policy
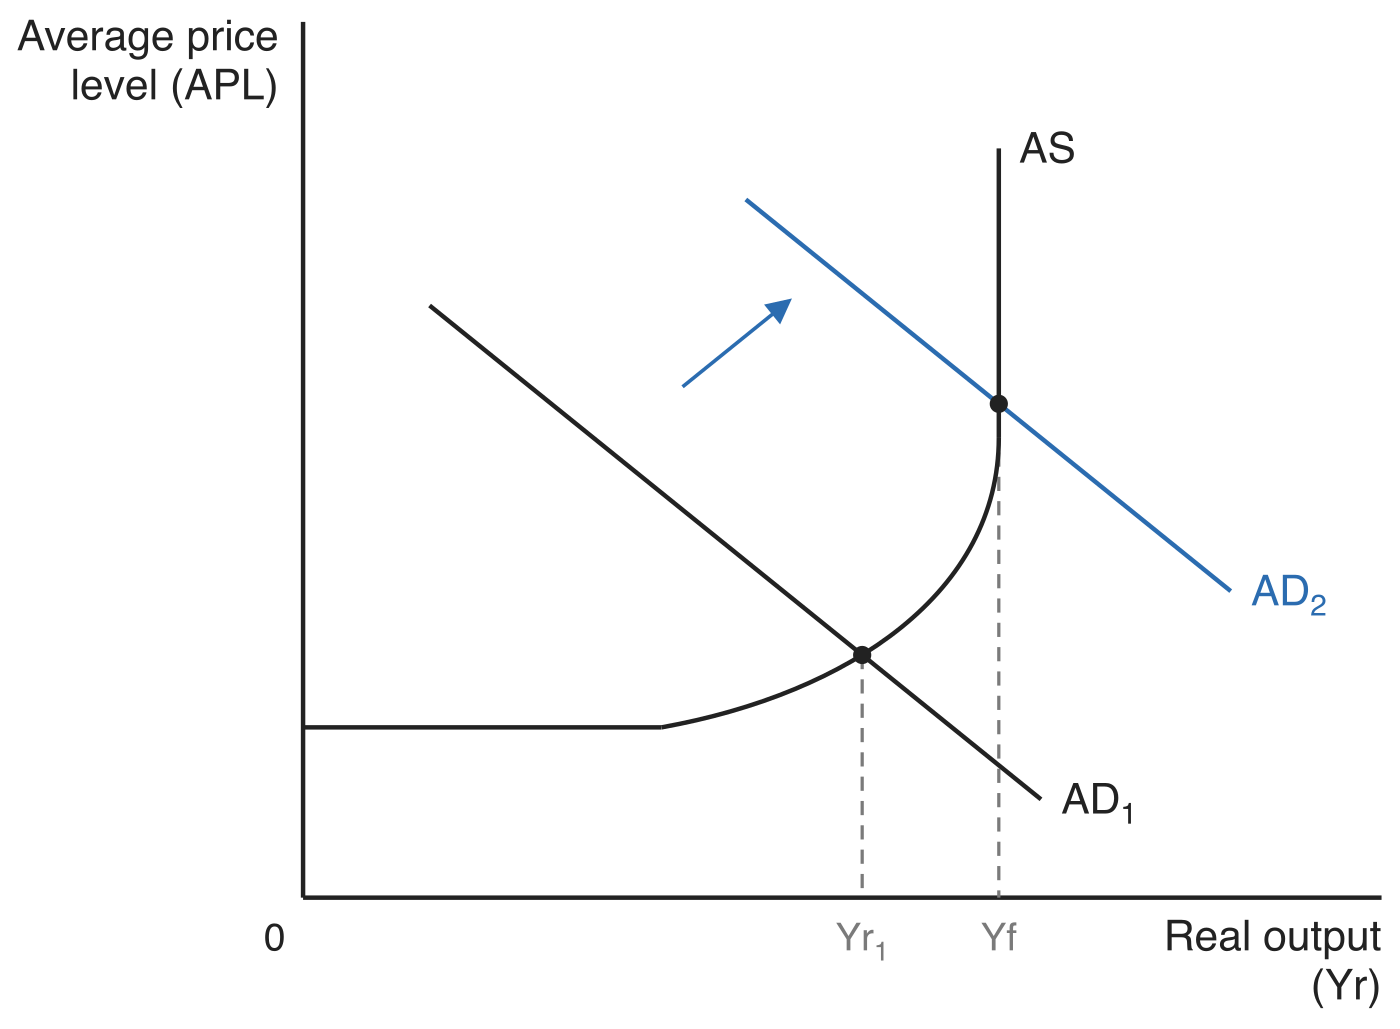
Expansionary policy lowers interest rates, stimulating economic activity through various channels. These effects shift AD to the right, promoting growth.
The Keynesian diagram below shows this. The economy starts where AD1 cuts the aggregate supply curve AS, at real output Yr1 below the full employment level Yf, so there is a recessionary (or deflationary) gap between Yr1 and Yf and cyclical unemployment is high. Lower interest rates raise consumption, investment, and net exports, shifting aggregate demand right to AD2 and lifting output to Yf, which closes the gap. As output approaches Yf the average price level (APL) is pushed up as well, and how much depends on the shape of the AS curve.
Effects on consumption
- Lower interest rates reduce borrowing costs for households, encouraging loans for durable goods and homes.
- Reduced incentives to save lead to higher spending.
- The housing market often sees significant boosts, acting as a key transmission mechanism.
Effects on investment
- Cheaper borrowing makes more projects viable for firms, such as constructing facilities or buying equipment.
- The opportunity cost of using retained profits for investments decreases.
Effects on net exports
- Lower domestic rates reduce returns for investors, leading to currency depreciation.
- A weaker currency makes exports cheaper and more competitive abroad, increasing export volumes.
Effects of contractionary monetary policy
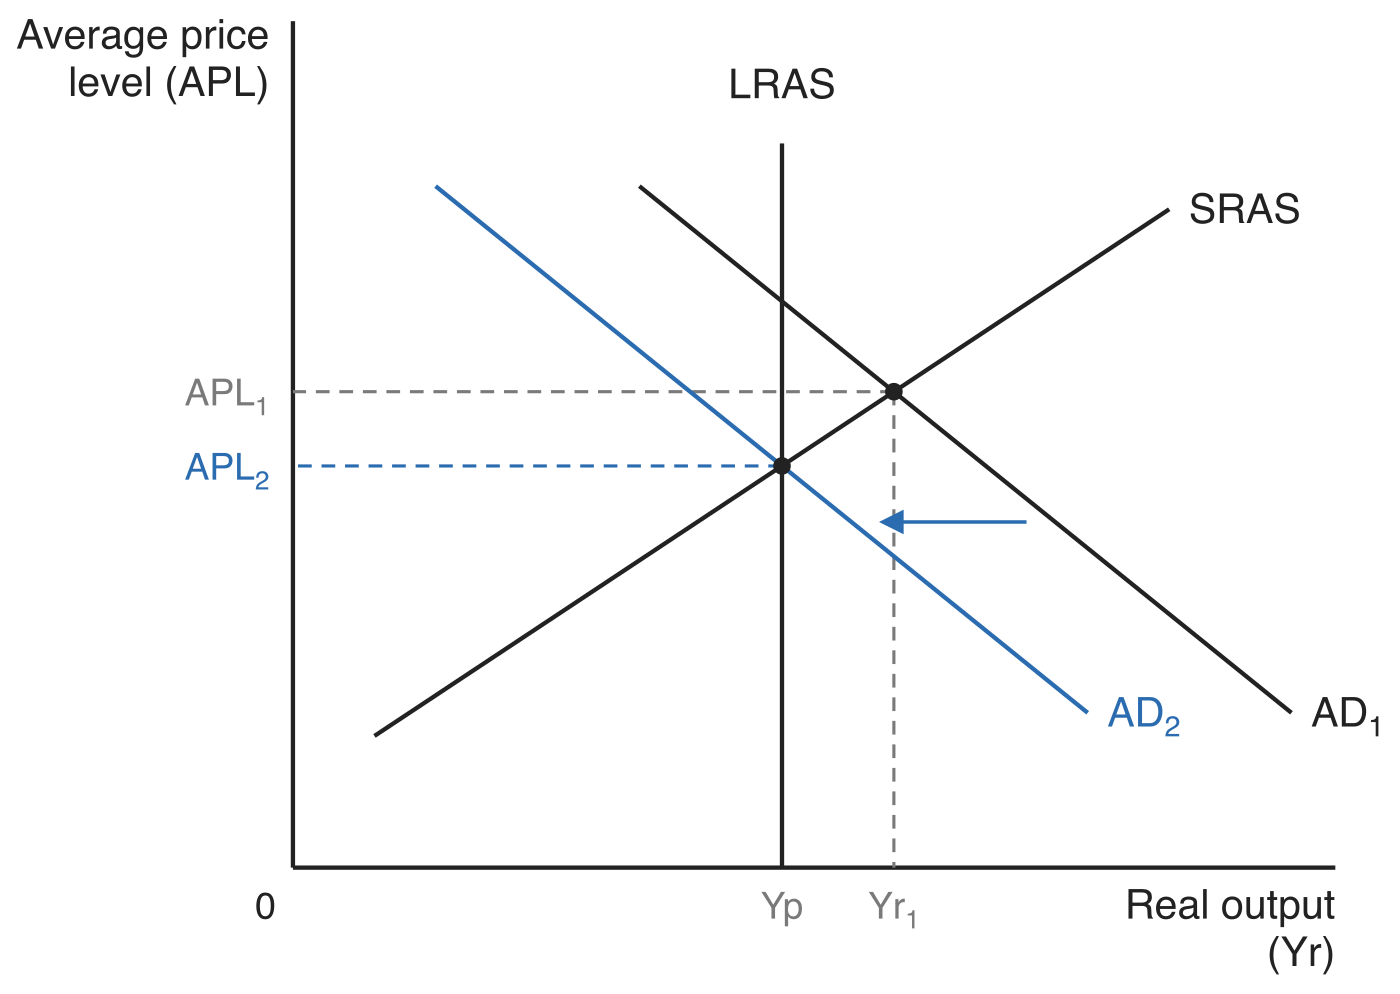
Contractionary policy raises interest rates, cooling the economy to control inflation. These effects shift AD to the left, slowing activity.
The Monetarist/New Classical diagram below shows this. AD1 cuts the short-run aggregate supply curve SRAS at real output Yr1, above the potential output Yp fixed by the long-run aggregate supply curve LRAS, so there is an inflationary gap between Yp and Yr1 and the average price level has been driven up to APL1. Higher interest rates cut consumption, investment, and net exports, shifting aggregate demand left to AD2, returning output to Yp and bringing the average price level down to APL2. Read that fall loosely: the aim of tighter policy is to slow inflation rather than to force prices down.
Effects on consumption
- Higher interest rates increase borrowing costs, reducing loans for durable goods and housing.
- Greater incentives to save lead to lower spending.
Effects on investment
- Costlier borrowing makes fewer projects profitable.
- The opportunity cost of using internal funds for capital rises.
Effects on net exports
- Higher domestic rates attract foreign investors, causing currency appreciation.
- A stronger currency makes exports more expensive and less competitive, decreasing export volumes.
Real interest rates and their implications
The real interest rate adjusts the nominal rate for inflation, reflecting the true cost of borrowing or return on saving. It influences economic decisions more accurately than the nominal rate alone.
Formula for real interest rate
rr = rn - p̂
Where:
- rr = Real interest rate
- rn = Nominal interest rate
- p̂ = Expected inflation rate
A simplified version uses actual inflation: real interest rate = nominal interest rate − inflation rate.
Effects of inflation and deflation on real interest rates
- During inflation - The real rate is lower than the nominal rate, benefiting borrowers as the effective cost of loans decreases.
- During deflation - The real rate is higher than the nominal rate, benefiting savers as returns effectively increase.
- Monetary policy becomes less effective in deflationary periods, as even low nominal rates can result in high real rates, discouraging borrowing.
Worked example - Calculating real interest rates
A country has a nominal interest rate of 4.50% and an inflation rate of 2.10%. Later, during deflation, the nominal rate is 1.80% with an inflation rate of -0.60%. Calculate the real interest rates for both scenarios.
Step 1: Identify the values
- First scenario: Nominal rate = 4.50%, inflation rate = 2.10%
- Second scenario: Nominal rate = 1.80%, inflation rate = -0.60%
Step 2: Calculate real rate for the first scenario
Step 3: Calculate real rate for the second scenario
Step 4: Interpretation
In the inflationary period, the real rate is 2.40%. During deflation, the real rate also becomes 2.40%, making borrowing more expensive despite the lower nominal rate.