3.12 - Phillips Curve
Origins and basic concept of the Phillips curve
The Phillips curve illustrates the inverse relationship between unemployment and inflation within an economy. It emerged as a key macroeconomic concept based on historical data analysis.
Development of the Phillips curve
Alban W. Phillips, a New Zealand economist working at the London School of Economics, introduced the Phillips curve in 1958. He examined UK data spanning 96 years, from 1861 to 1957, focusing on changes in money wages and unemployment rates. His findings revealed an inverse correlation: low unemployment corresponded with rapid wage increases, while high unemployment led to slower wage growth or even declines.
Extension to inflation
The relationship extends beyond wages to general price inflation. Wages constitute a major part of production costs, and businesses often apply a mark-up to these costs when setting prices. As a result, the curve depicts an inverse link between the inflation rate and the unemployment rate: lower unemployment tends to drive up inflation as firms compete for workers, pushing wages and prices higher.
The diagram below is that Phillips curve, with the inflation rate (π) up the vertical axis and the unemployment rate (U) across the horizontal axis. It slopes downwards throughout, so every fall in unemployment along it comes with faster inflation, and every rise in unemployment comes with slower inflation.
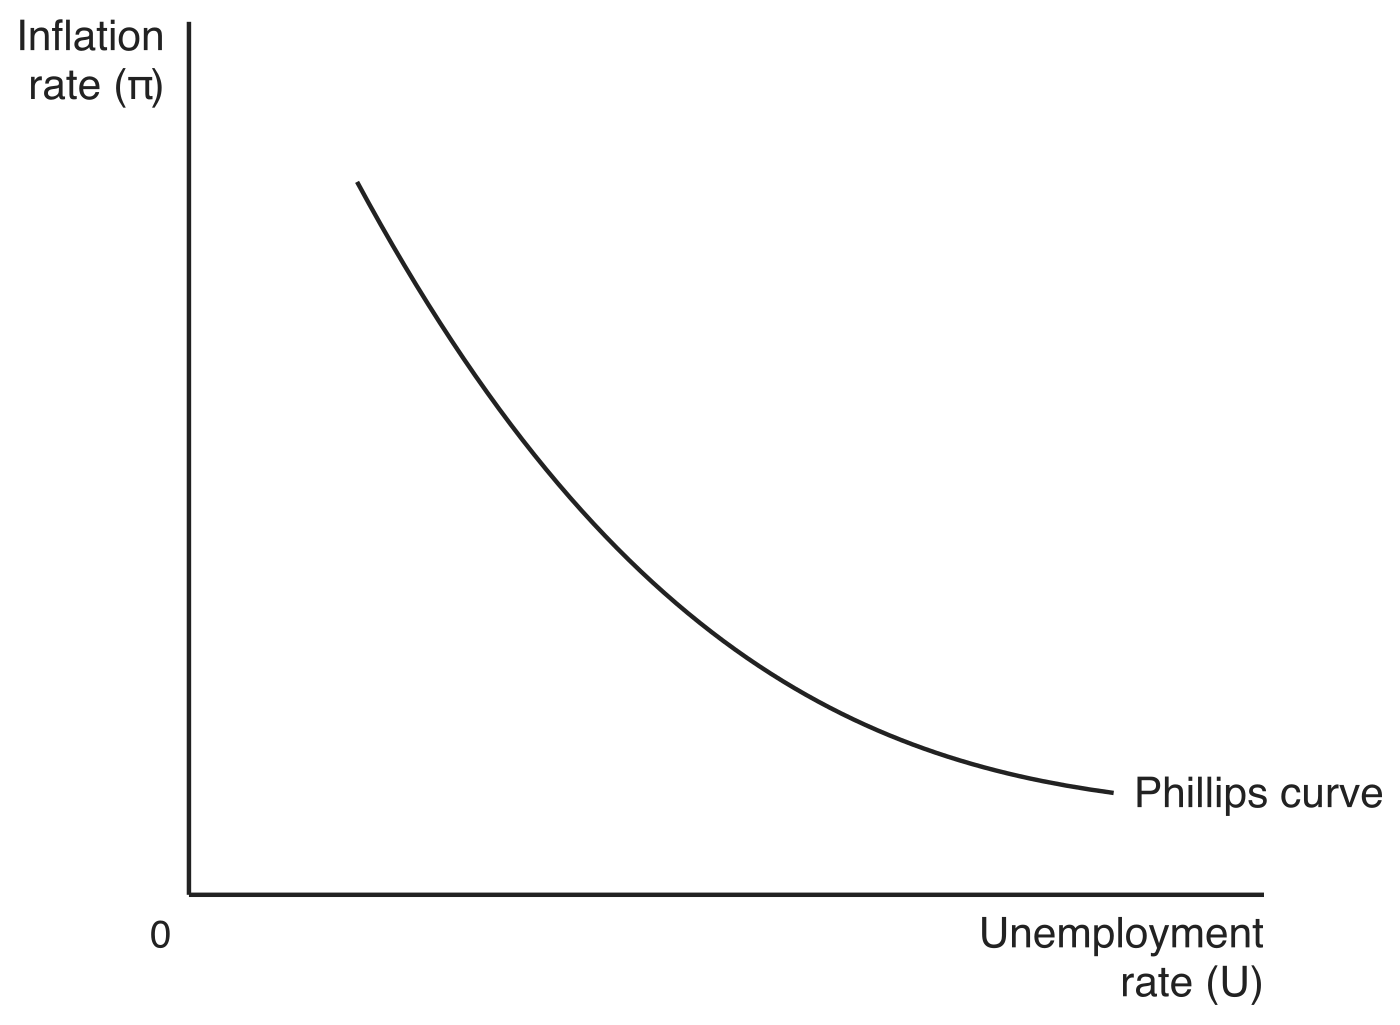
Relationship between unemployment and inflation
The Phillips curve highlights how labour market conditions influence wage and price dynamics.
Dynamics in different labour market conditions
- Low unemployment (tight labour market) - Employers compete for limited workers, leading to substantial wage increases to attract and retain staff.
- High unemployment (slack labour market) - Firms can hire without significant wage hikes, resulting in minimal wage growth or potential decreases.
Compatibility with aggregate demand and supply
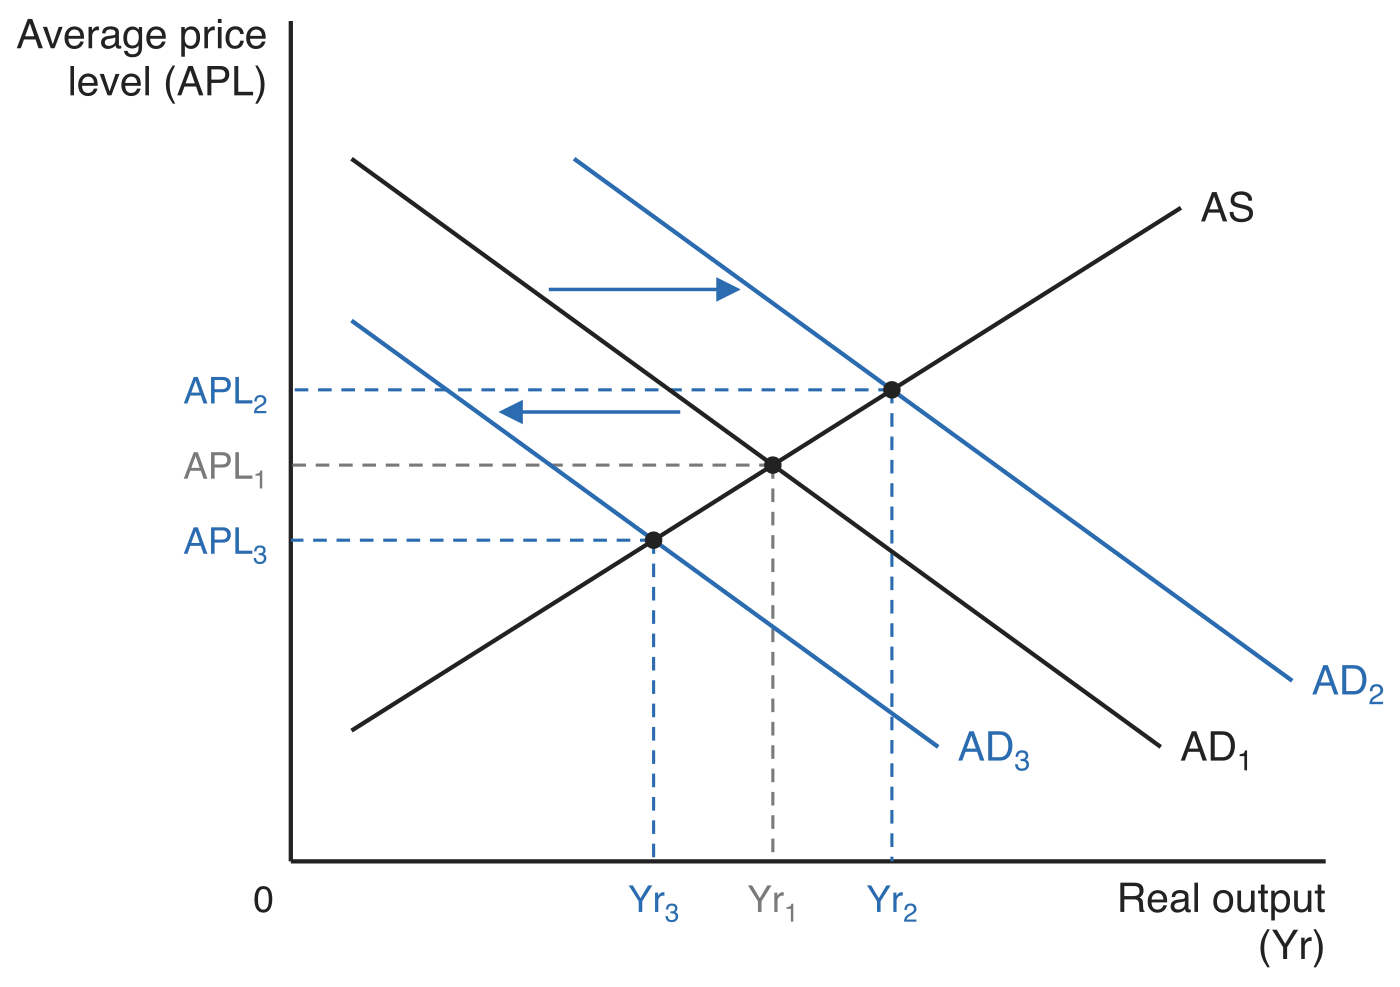
The Phillips curve fits within the aggregate demand (AD) and aggregate supply (AS) framework. The diagram below plots the average price level (APL) against real output (Yr). The economy starts where AD1 cuts AS, at real output Yr1 and average price level APL1. An increase in aggregate demand shifts the curve rightwards to AD2, raising real output to Yr2 and the average price level to APL2; a decrease shifts it leftwards to AD3, cutting real output to Yr3 and the average price level to APL3.
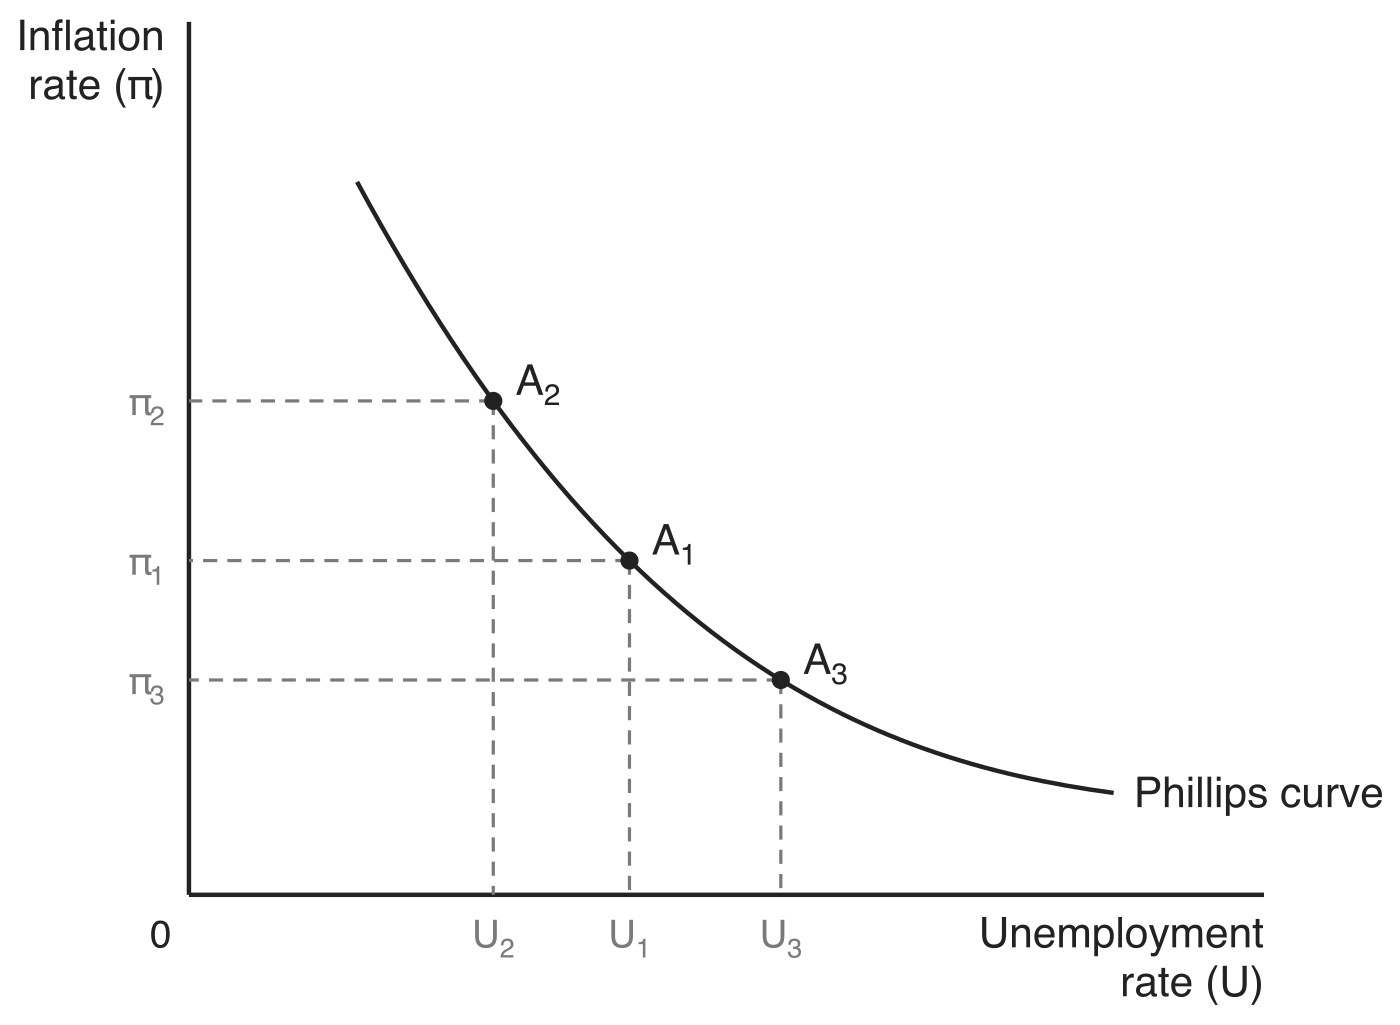
The diagram below puts those same three outcomes on the Phillips curve, with the inflation rate (π) against the unemployment rate (U). The starting position is point A1, where inflation is π1 and unemployment is U1. After the increase in AD, the extra output means firms take on more workers, so unemployment falls to U2, while the higher average price level means inflation rises to π2: the economy has moved along the curve to A2. After the decrease in AD, the lower level of activity pushes unemployment up to U3 and inflation down to π3, moving the economy to A3. Both movements trace out the inverse relationship the Phillips curve describes, which is why the curve sits comfortably alongside the AD and AS model.
Policy perspective on the trade-off
Policymakers initially saw the Phillips curve as offering a range of options: they could pursue lower unemployment at the cost of higher inflation, or prioritise low inflation by accepting higher unemployment.
The short-run and long-run Phillips curves
Distinctions between short-run and long-run perspectives on the Phillips curve emerged from later economic analysis, revealing limitations in the original model.
Short-run Phillips curve
The short-run Phillips curve (SRPC) slopes downwards, showing a trade-off where lower unemployment coincides with higher inflation. This reflects temporary adjustments in the economy, such as responses to demand changes.
Long-run Phillips curve
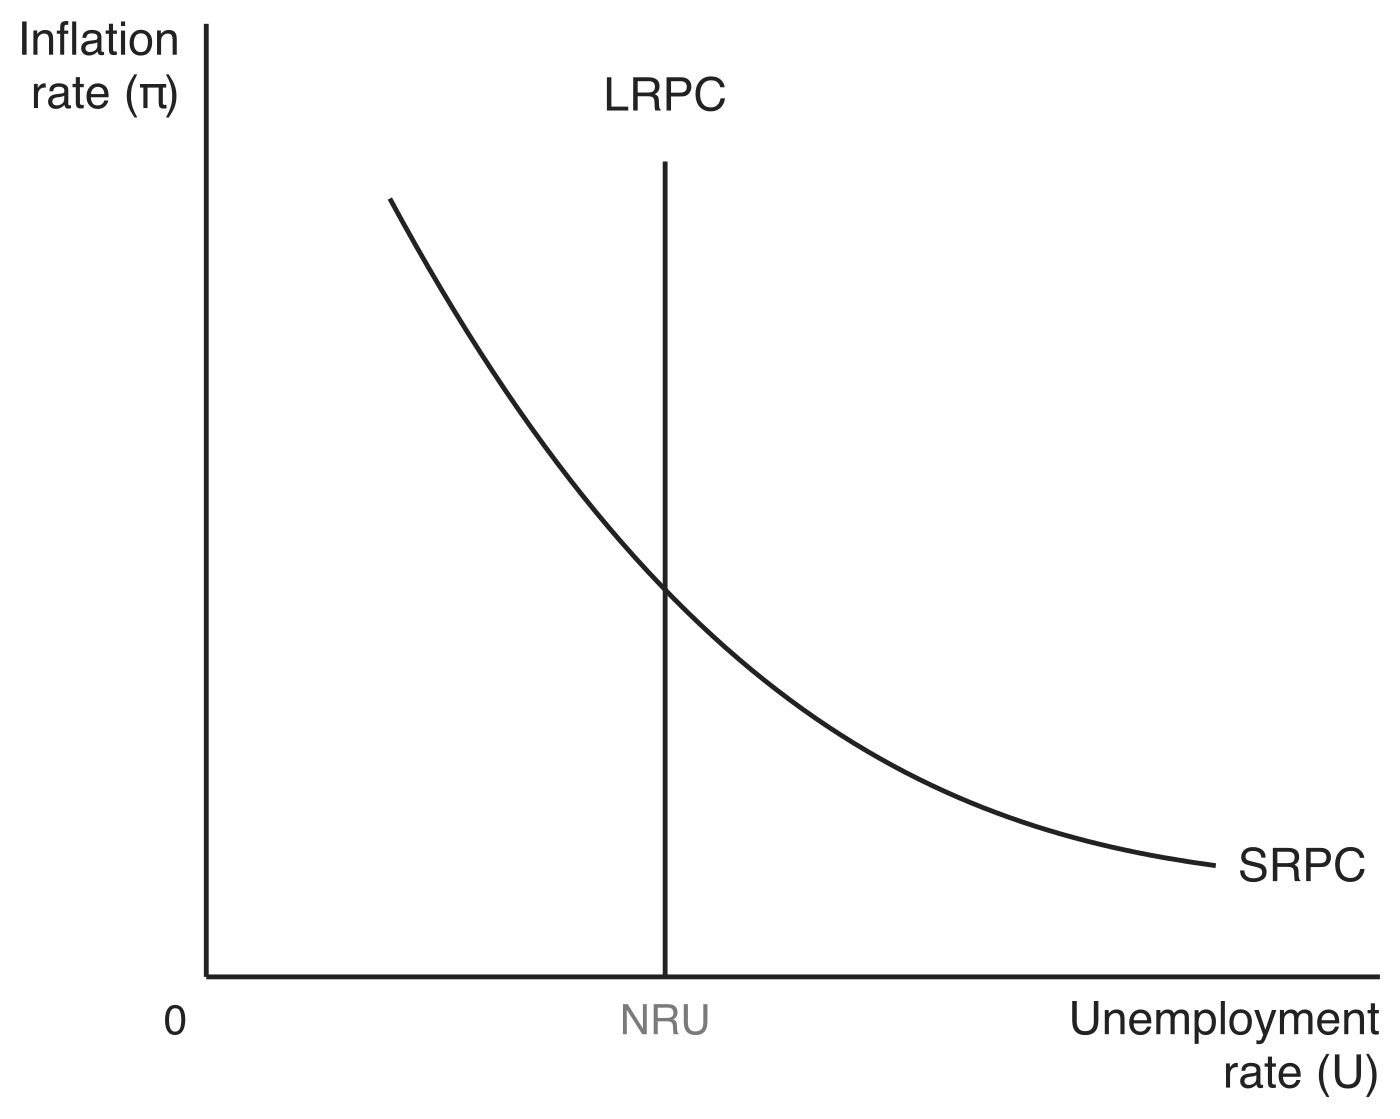
In contrast, the long-run Phillips curve (LRPC) is vertical, positioned at the natural rate of unemployment (NRU). This indicates no lasting trade-off: attempts to reduce unemployment below the NRU only result in accelerating inflation without sustained employment gains. The NRU represents the unemployment level consistent with stable inflation, excluding cyclical factors.
The diagram below shows the two curves together, with the inflation rate (π) against the unemployment rate (U). The downward-sloping SRPC pairs a different rate of inflation with every unemployment rate, while the vertical LRPC stands at the NRU, so in the long run that one unemployment rate is consistent with any rate of inflation at all.
The NRU is not fixed; it fluctuates over time and differs between countries due to factors like labour market policies, skills mismatches, and demographic shifts.
The expectations-augmented Phillips curve
Critiques of the original Phillips curve led to an enhanced version incorporating expectations, explaining why the trade-off breaks down over time.
Key elements of the expectations-augmented Phillips curve
Developed by economists like Milton Friedman and Edmund Phelps, this model distinguishes short-run from long-run effects. It attributes short-run trade-offs to workers' adaptive expectations, where they base future inflation predictions on past rates, leading to money illusion, a failure to immediately recognise real wage changes.
Process when reducing unemployment below the natural rate
Expansionary policies aimed at lowering unemployment below the NRU trigger a sequence of events:
- Inflation rises faster than anticipated.
- Real wages fall temporarily, encouraging firms to increase production and hiring.
- Unemployment drops below the NRU in the short run.
- Workers eventually update their expectations and seek higher nominal wages to restore real wages.
- As real wages return to equilibrium, firms reduce hiring, and unemployment reverts to the NRU.
This process demonstrates that short-run gains are illusory, with only higher inflation persisting in the long run.
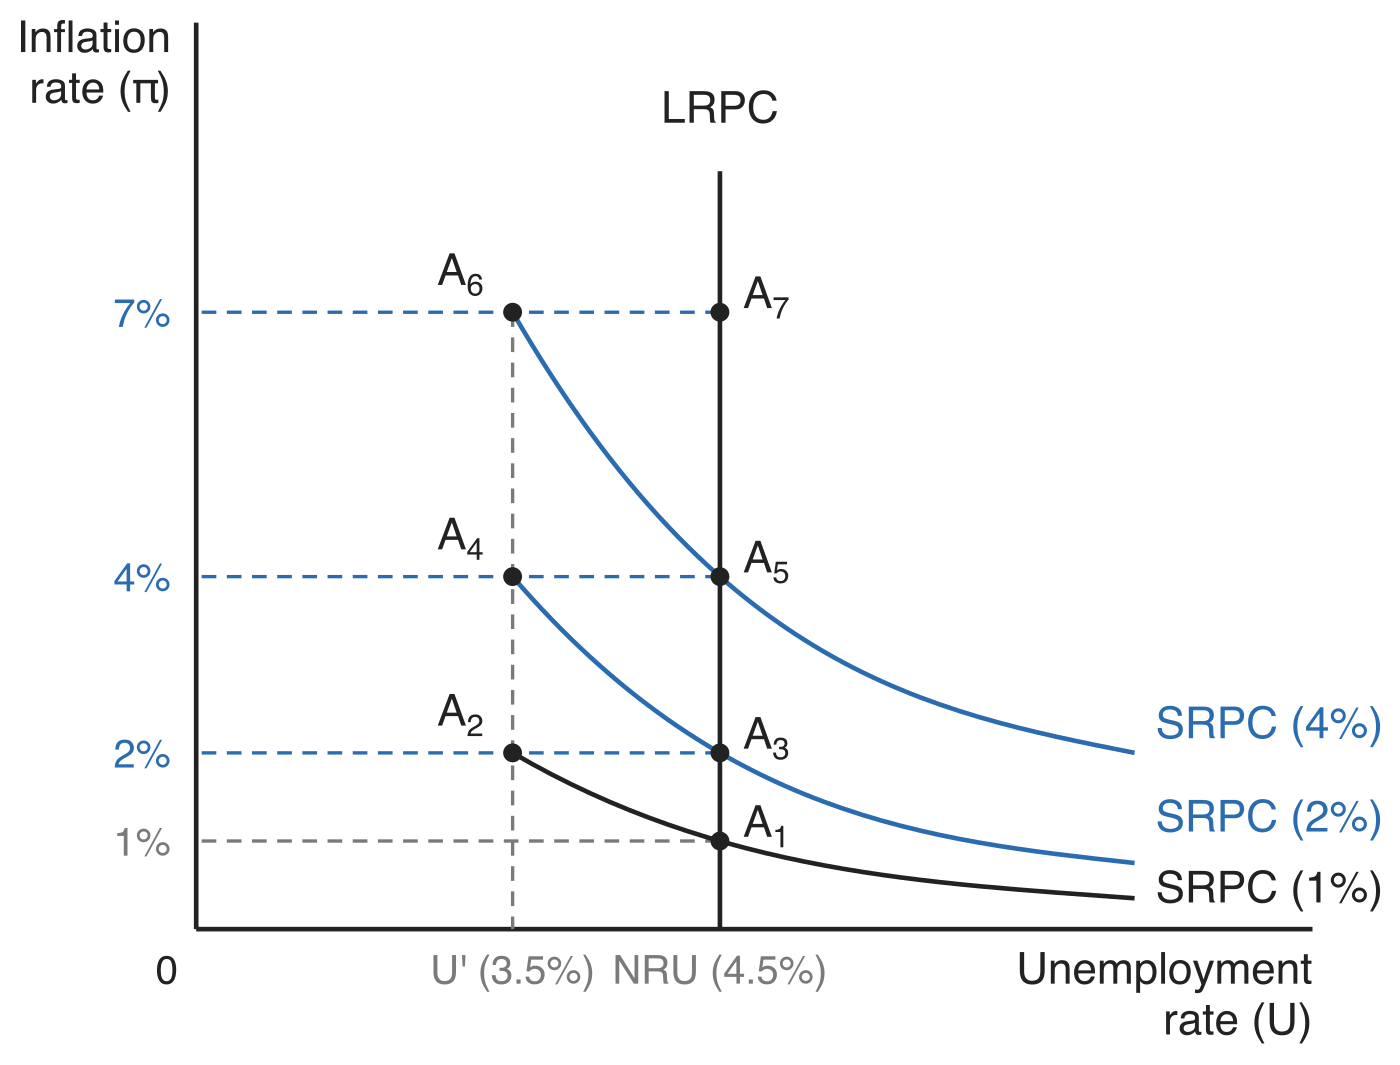
The diagram below traces the sequence, with the inflation rate (π) against the unemployment rate (U). The economy starts at A1 on SRPC (1%): unemployment sits at the NRU (4.5%) and inflation has been 1% for long enough that workers expect 1% again. Expansionary policy takes inflation to 2%, and because money wages are fixed in the short run the real wage falls, so firms hire more and unemployment drops to U' (3.5%). That is the move along SRPC (1%) from A1 to A2. Once workers see that inflation is really 2% they demand higher money wages, the real wage is restored, firms cut hiring, and unemployment returns to the NRU at A3 - the short-run curve has shifted right to SRPC (2%), because 2% is now the rate workers expect.
Repeating the exercise repeats the pattern at a higher cost. Getting unemployment back down to U' (3.5%) now takes 4% inflation, moving the economy along SRPC (2%) to A4, and once expectations adjust again it returns to the NRU at A5 on SRPC (4%). A third attempt would need 7% inflation to reach A6 before the economy settled back at A7. Every point at which unemployment has returned to the NRU sits on the vertical LRPC, so all the sequence leaves behind is higher inflation.
Historical breakdown of the original relationship
In the 1970s, the stable inverse link between inflation and unemployment weakened, as economies experienced high inflation alongside high unemployment (stagflation), supporting the expectations-augmented view.
Policy considerations and recent challenges
Insights from the Phillips curve influence economic policy, but recent trends have questioned its reliability.
Implications for government policy
Governments should avoid using demand-side measures to force unemployment below the NRU, as this leads to accelerating inflation without long-term benefits. Instead, policies should target supply-side improvements to potentially lower the NRU itself.
Recent economic observations
In some economies, unemployment has reached record lows without sparking significant inflation, challenging traditional Phillips curve predictions.
Possible explanations for low inflation despite low unemployment
- Challenges in measuring unemployment types - Distinguishing between structural unemployment and cyclical unemployment can be difficult, obscuring the true NRU.
- Labour market re-entry - Discouraged workers returning to the job market may expand the labour supply, suppressing wage pressures.
- Anchored inflation expectations - Persistently low expectations of future inflation can prevent wage and price spirals even as unemployment falls.